If you’re having trouble reading this, click here.
MONDAY ECONOMIC REPORT
Output Expands Despite Mounting Price Pressures
October 19, 2026
By Victoria Bloom and Michael Green
Manufacturing-Focused Weekly Toplines
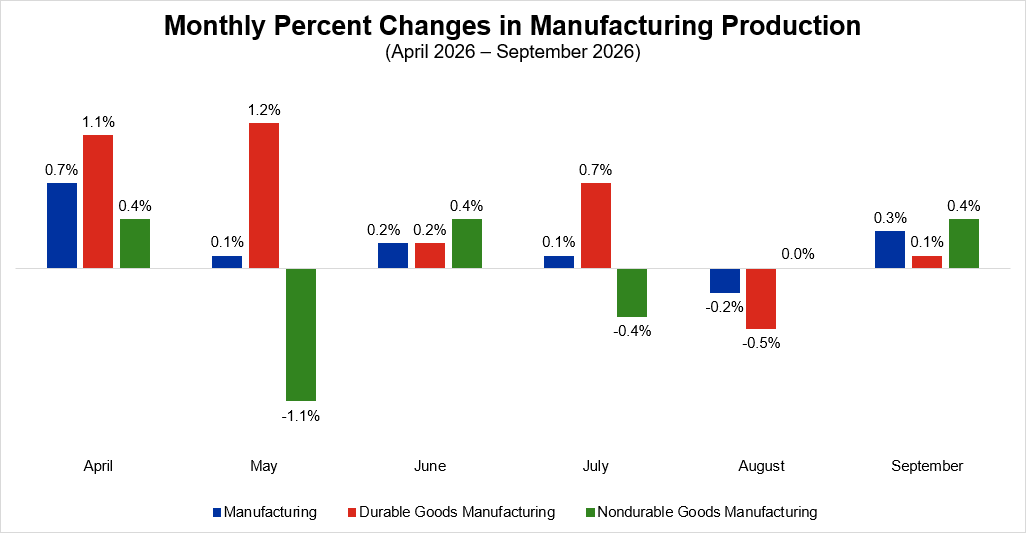
Manufacturing production recovers in September: Manufacturing output stepped up 0.3% after ticking down 0.2% in August. At the same time, manufacturing production increased 1.1% from the year prior. Capacity utilization for manufacturing was 75.9%, up 0.1 percentage point from August and 1.0% over the past year. Capacity utilization for manufacturing remained 2.3 percentage points below its long-run average from 1972 to 2025.
Why it matters: After manufacturing production pulled back in August, the 2026 upward trend in output returned, with a majority of industry groups exhibiting improvements. That said, the growth rate is slowing from earlier in the year, while certain sectors, such as computer and electronic parts and machinery, continue to have outsized gains.
Consumer price growth accelerates: In September, consumer prices increased 0.6% from August and 3.7% over the year, up from the 3.4% annual rise in August and higher than expectations. Core CPI, which excludes more volatile energy and food prices, rose 0.3% from August and 2.6% over the year, up from the 2.4% 12-month increase the month prior.
What it means: The headline inflation rate is still well above the Federal Reserve’s 2.0% target, driven in part by rising energy prices stemming from the war in the Middle East. Core inflation also remains elevated, though well below the headline rate. Federal Reserve officials raised their interest rate target at their September meeting, but markets anticipate that the Federal Open Market Committee will hold rates steady at its meeting later this month, even as risks to its inflation mandate persist.
Meanwhile, producer prices continue to soar: Wholesale prices, which tend to give an early look at where consumer prices are heading, jumped 1.3% in September, the greatest monthly increase since March 2022 and up from the 0.5% advance in August. Over the year, producer prices surged 6.3%, while prices for final demand excluding foods, energy and trade services climbed 5.0%. Prices for services grew 0.8% in September, while prices for goods jumped 2.6%, the largest increase since the data were first calculated in December 2009.
Why it matters: Energy prices continue to drive the increase in the headline consumer price index, but producers are feeling price pains more broadly and acutely, partly due to energy affecting the price of transportation services and a wide range of commodities that producers utilize. Overall, energy prices jumped 10.8% in September as gasoline prices surged 20.3%. At the same time, increased demand for certain goods, such as electronic components and accessories, continues to drive up prices in other areas.
Import and export costs keep rising: In September, U.S. import prices for manufacturing climbed 6.6% over the year, with all subsectors experiencing price increases. Petroleum and coal products manufacturing recorded the largest over-the-year import price increase, surging 50.6%. On the other hand, import prices for electrical equipment, appliance and component manufacturing ticked up just 0.5% from September 2025. Meanwhile, U.S. export prices for manufacturing advanced 9.0% over the year, with petroleum and coal products manufacturing exhibiting the largest rise (48.8%).
What it shows: Increased import prices were widespread in September, but over-the-year fuel import price increases remain outsized compared to other categories amid the conflict in the Middle East. As the conflict continues, import and export prices are expected to remain elevated.
Manufacturing activity slowed in Philadelphia but picked up in New York: In October, Philadelphia’s regional manufacturing activity expanded at a slower pace, with the index for general business activity falling from 37.8 to 20.9. After dropping 20.7 points in September, expectations for future business activity declined 19.9 points to 33.0 in October. Meanwhile, manufacturing activity in New York state expanded at a faster pace in October, with the headline business conditions index surging 17.9 points to 25.5. Firms in New York remained optimistic about the six-month outlook, though expectations softened in October, with the future business activity index decreasing 8.0 points to 21.0.
Why it matters: While growth was uneven in Philadelphia and New York in October, future growth indicators weakened in both regions. Expectations remain positive but are slowing across the board as manufacturers in Philadelphia and New York anticipate decreases in activity in the coming months, which could be partly a result of persistent price pressures.
This Week’s Economic Indicators
Monday, Oct. 19 NAHB Housing Market Index New Residential Construction
Tuesday, Oct. 20 Pending Home Sales
Wednesday, Oct. 21 None
Thursday, Oct. 22 Kansas City Fed Manufacturing Survey
Friday, Oct. 23 University of Michigan Consumer Sentiment Index S&P Global Flash PMI
Deeper Dive
Industrial Production and Capacity Utilization: Industrial production rose 0.7% in September, while manufacturing output stepped up 0.3% after ticking down 0.2% in August. At 98.4% of its 2017 average, manufacturing production increased 1.1% from September 2025. Capacity utilization for manufacturing was 75.9%, up 0.1 percentage point from August and 1.0% over the past year. Capacity utilization for manufacturing remained 2.3 percentage points below its long-run average from 1972 to 2025.
Consumer Price Index: In September, consumer prices increased 0.6% from August and 3.7% over the year, up from the 3.4% annual rise in August and higher than expectations. Core CPI, which excludes more volatile energy and food prices, rose 0.3% from August and 2.6% over the year, up from the 2.4% 12-month increase the month prior.
Producer Price Index: The Producer Price Index for final demand (also known as wholesale prices) rose 1.3% in September, up from the 0.5% advance in August. Over the year, producer prices increased 6.3%, up from the 5.6% gain in August. Meanwhile, prices for final demand excluding foods, energy and trade services climbed 5.0% from September 2025, up from the 4.8% increase in August.
U.S. Import and Export Price Indexes: U.S. import prices increased 1.1% in September, after rising 0.5% in August, driven by higher fuel and nonfuel import prices. Over the year, import prices jumped 8.1%, the largest annual gain since July 2022. Meanwhile, U.S. export prices rose 2.2% in September, led by higher prices for both agricultural and nonagricultural exports. Over the past year, export prices climbed 11.6%.
In September, U.S. import prices for manufacturing climbed 6.6% over the year, with all subsectors experiencing price increases. Petroleum and coal products manufacturing recorded the largest over-the-year import price increase, surging 50.6%. On the other hand, import prices for electrical equipment, appliance and component manufacturing ticked up just 0.5% from September 2025. Meanwhile, U.S. export prices for manufacturing advanced 9.0% over the year, with petroleum and coal products manufacturing exhibiting the largest rise (48.8%).
Philadelphia Fed Manufacturing Business Outlook Survey: In October, Philadelphia’s regional manufacturing activity expanded at a slower pace, with the index for general business activity falling from 37.8 to 20.9. This month, 41.2% of firms reported increases in activity, while 20.3% cited decreases. New order growth also slowed, falling from 29.2 to 4.3, while the shipments index declined from 27.7 to 15.3. Meanwhile, the employment index stepped down 2.7 points to 9.1, and the average employee workweek dropped 10.5 points to 7.5. The prices paid index decreased from 48.6 to 43.2, while the prices received index rose from 31.3 to 40.1. As has been the case for many months, the prices received index remained lower than the prices paid index, but that gap is starting to close, indicating that manufacturers have gained increased pricing power amid stronger demand and have to absorb a smaller portion of higher costs paid.
Empire State Manufacturing Survey: Manufacturing activity in New York state expanded at a faster pace in October, with the headline business conditions index surging 17.9 points to 25.5. The new orders index climbed 21.2 points to 23.2, while the shipments index turned positive, increasing 16.3 points to 13.1. The unfilled orders index rose 8.1 points to 14.0, while inventories stepped up 2.7 points to 11.6. Delivery times lengthened, and supply availability worsened.
NFIB Small Business Survey: The NFIB Small Business Optimism Index edged down 0.8 points to 97.9 in September, falling slightly below the 52-year average of 98. The decline was driven by worsening expectations for business conditions and fewer reports that it is a good time to expand. Of the 10 components in the index, three increased, six decreased and one stayed the same. Meanwhile, the Uncertainty Index rose 1 point to 90, still well above the 51-year average (68) and above the average since 2016 (80).
Manufacturing Inventories and Sales: In August, manufacturers’ sales stayed the same from July but rose 8.5% from August 2025. Manufacturers’ inventories increased 0.5% in August and 2.6% from the same month a year ago. The manufacturers’ inventories/sales ratio stood at 1.48 at the end of August, up slightly from 1.47 the prior month but down from 1.56 in August 2025.
Real Earnings: Real average hourly earnings decreased 0.5% in September as a result of a 0.1% rise in average hourly earnings combined with a 0.6% uptick in inflation. Meanwhile, real average weekly earnings declined 0.5% due to the change in real average hourly earnings combined with no change in the average workweek in September. In the past year, real average hourly earnings stepped down 0.7%, while the average workweek increased 0.6%, resulting in a 0.1% fall in real average weekly earnings compared to September 2025.
For production and nonsupervisory employees, real average hourly earnings moved down 0.6% in September as a result of a 0.2% increase in average hourly earnings and a 0.7% rise in inflation. Real average weekly earnings for this group decreased 0.5% due to the change in real average hourly earnings and no change in the average workweek. In the past year, real average hourly earnings for this group declined 0.6%, and the average workweek rose 0.3%, resulting in a 0.3% decrease in real average weekly earnings from September 2025.
Existing Home Sales: Existing home sales increased 1.5% in September but declined 2.2% over the year. Housing inventory moved up to 1.60 million units, rising 1.9% from August and 4.6% from last year. The median existing home price was $417,500, up 1.3% from last year. In September, the South and West posted monthly increases, while the Northeast declined and the Midwest stayed the same.
Single-family home sales increased 2.0% from August but decreased 1.9% from September 2025, with the median price growing 1.2% from last year to $422,700. Condo and co-op sales fell 2.8% from August and 5.4% from last year to 350,000 units in September. Meanwhile, the median price for condos and co-ops advanced 1.2% from the prior year to $363,700.
Homes typically remained on the market for 33 days in September, up from 31 days in August but unchanged from September 2025. First-time buyers made up 31% of sales in September, up slightly from 30% in both August and September 2025.